
Affirm has been on fire lately. In the past six months alone, the company’s stock price has rocketed 54.3%, reaching $71.22 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Affirm, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Affirm Not Exciting?
We’re glad investors have benefited from the price increase, but we’re passing on Affirm for now. Here are two reasons we avoid AFRM, plus one stock we’d rather own.
1. Previous Growth Initiatives Have Lost Money
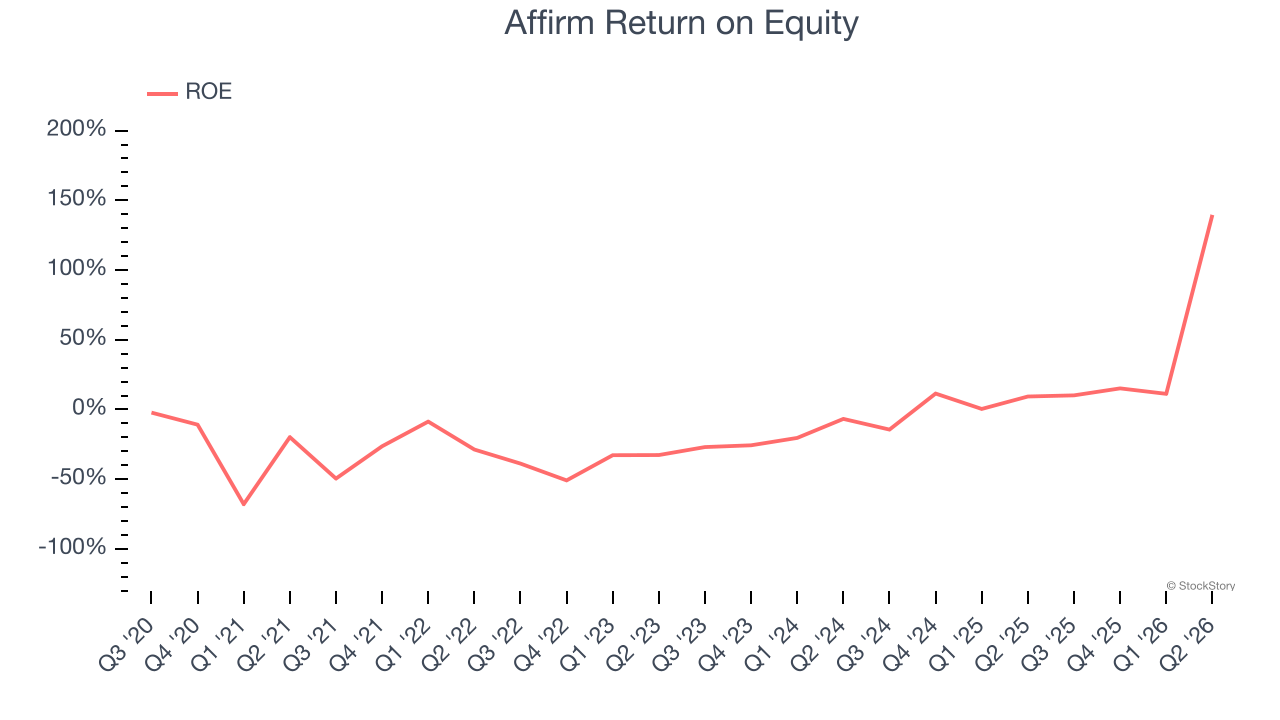
Return on equity, or ROE, quantifies financial firm profitability relative to shareholder equity — an essential capital source for these institutions. Over extended periods, superior ROE performance drives faster shareholder wealth compounding through reinvestment, share repurchases, and dividend growth.
Over the last five years, Affirm has averaged an ROE of negative 8.3%, a bad result not only in absolute terms but also relative to the majority of firms putting up 25%+. It also shows that Affirm has little to no competitive moat.
2. High Debt Levels Increase Risk
Affirm reported $2.60 billion of cash and $9.99 billion of debt on its balance sheet in the most recent quarter.
As investors in high-quality companies, we primarily focus on whether a company’s profits can support its debt.
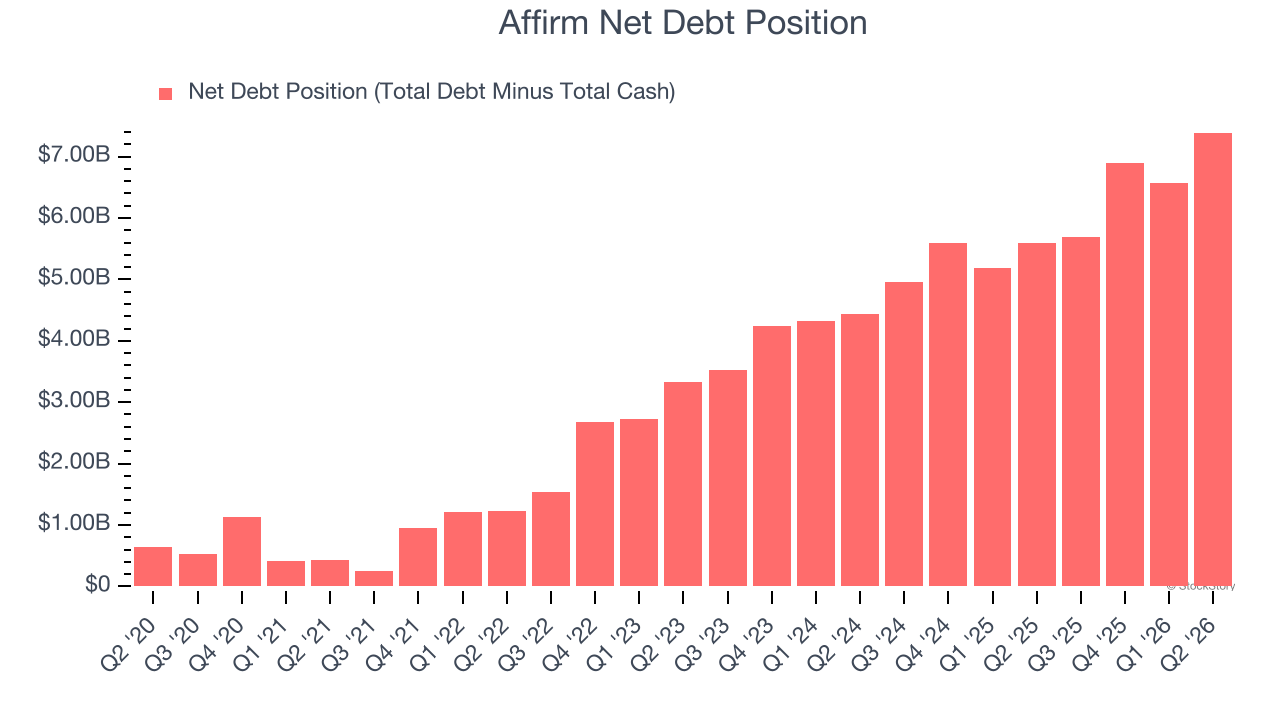
With $1.26 billion of EBITDA over the last 12 months, we view Affirm’s 5.9× net-debt-to-EBITDA ratio as inadequate. The company’s lacking profits relative to its borrowings give it little breathing room, raising red flags.
Final Judgment
Affirm isn’t a terrible business, but it doesn’t pass our bar. After the recent surge, the stock trades at 18.7× forward P/E (or $71.22 per share). Beauty is in the eye of the beholder, but we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. We’d recommend looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.